Key Takeaways
- An IMF official warns that AI could cause declines in government revenues around the world.
- This could trigger searches for new sources aside from traditional income taxes.
- It could also lead governments to re-examine the current tools for taxing international income.
- Midterms shouldn't change U.S. approach to global minimum tax.
- OECD mulling update to tax rules on intangible assets.
As it reshapes the economy and our everyday lives, artificial intelligence is also changing every part of the tax system—in the U.S. and around the world.
International Monetary Fund Managing Director Kristalina Georgieva noted last week that it could make dramatic changes in government revenues, something that countries will need to prepare for.
“AI may raise growth, but it could also reduce labor income, increase inequality, and erode the tax base,” Georgieva wrote in a blog post on the IMF’s website. “With debt already high, policymakers will need to make hard choices.”
Tax systems tend to raise more through income than increases in wealth or capital. Georgieva contends that if AI tips the balance more towards capital, that could leave countries with a shortfall to contend with, just as the demands on infrastructure and economic support could be crucial.
Of course, there are many competing theories about how AI might reshape the economy. Whatever happens, there is sure to be change and instability, making governments’ decisions potentially more difficult.
Should there be a drop in revenue, countries will no doubt look for new ways to boost their budget, including through the international system. The current multinational projects to shore up corporate taxes and reduce profit-shifting and avoidance largely began with the 2008 financial crisis, and the subsequent shortfalls in revenue and scaling back of public services.
If it happens again, it would be while AI could be making profit even more intangible and global. New questions are sure to arise about how to apportion income tied to data centers, new formulas or inventions, and users around the world. Will governments need new tools to try to capture income they believe is rightfully theirs? Will this put increasing strain on the already-testy issue of taxing digital income?
In the meantime, the global minimum tax is off to a potentially rocky start, and momentum to create a new international system at the United Nations continues to build. International cooperation, or the lack of it, could be pivotal in how this plays out.
Noteworthy Items This Week
The problem is that lucrative tax breaks in Republicans’ 2025 tax law — like immediate deductions of capital spending and research-and-development costs — are driving their federal tax liabilities to values far below their liability under the so-called base erosion and anti-abuse tax, or BEAT.
The stark mismatch between domestic corporate tax liability and their BEAT liability triggers the anti-abuse tax, requiring companies to pay the difference between the two. To mitigate BEAT tax, practitioners said, some companies are resorting to waiving their deductions or even liquidating their foreign subsidiaries to sidestep exposure to the levy altogether.
How The Midterms Are Likely To Shape Tax Policy – Natalie Olivo, Law360 Tax Authority ($):
In addition, specialists expect that the White House will continue to ensure that countries adopt a safe harbor that would effectively exempt U.S. companies from a 15% global minimum tax known as Pillar Two.
Nearly 150 countries agreed to the side-by-side safe harbor in January, which insulates multinational corporations from Pillar Two taxes if they are based in a jurisdiction that imposes its own minimum tax requirements. While the safe harbor is technically available to any country with a qualifying tax regime, the Organization for Economic Cooperation and Development, which led Pillar Two negotiations, has so far recognized only the U.S. as meeting the criteria..
OECD’s Intangibles Transfer Pricing Rules in Line for a Rethink – Somesh Jha, Bloomberg Tax ($):
The so-called DEMPE framework—development, enhancement, maintenance, protection, and exploitation—was included in the OECD’s 2015 transfer pricing guidelines. But the Paris-based organization hasn’t had the opportunity to study how it’s working in practice, Saranee de Silva, a senior OECD policy adviser, told the International Fiscal Association 2026 Melbourne Congress.
“We haven’t had the chance to go back to basics and discuss the practical implications of how it’s operating over the last 10 years,” de Silva said.
Supply Chain Concerns May Propel Advanced Manufacturing Credit – Marie Sapirie, Tax Notes ($):
The United States still depends on China for many upstream and midstream parts of the supply chains for battery, solar, and other clean energy technologies, a fact that sometimes has lawmakers wringing their hands. The drumbeat for change has so far been faint in the run-up to the November elections, but is poised to grow louder, and a recent report from Crux, a capital platform for clean energy projects, suggests why.
Public Domain Superhero of the Week
Every week, a new character from the Golden Age of Comics, who’s fallen out of use.
This week’s entry: Commando Ranger
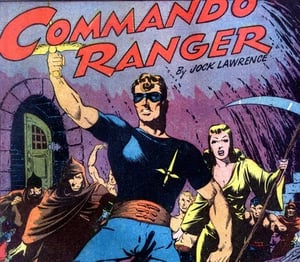
Debut Year: 1943
Debut Publication: Ranger Comics #13
Origin Story: A scientist, adventurer and Olympic boxer who studied how to apply mind over matter for years in Tibet, he fights for the Allies in World War II.
Superpowers: Aside from his amazing strength, he uses a winged dagger.
Eide Bailly's International Tax Team and our affiliates at HLB, The Global Advisory and Accounting Network, stand ready to assist with your worldwide tax needs.