Key Takeaways
- A new paper from two former Treasury officials argues that bolstering the corporate tax can help tackle the mounting federal debt.
- Their plan would include fully implementing the 15% global minimum tax agreed to by the Biden Administration.
- While Democrats won’t have the power to push for its recommendations, it shows where their focus could be.
- Inconsistent implementation of Pillar Two spooking taxpayers.
- Germany to tax sweet, non-alcoholic drinks.
After the national debt exceeded $40 trillion—and over 125% of U.S. gross domestic product—fiscal issues have returned to Washington policy debates.
Adding to the discussion are professors Kimberly Clausing and Natasha Sarin, who released last week a paper titled “$15 Trillion on the Table in 2029: Ordinary Taxes to Meet an Extraordinary Fiscal Moment,” calling for several tax changes to raise new revenue and chip away at the deficit.
Both of the authors served in the Department of the Treasury during the Biden Administration, and Clausing was instrumental in the Pillar Two agreement at the Organization for Economic Cooperation and Development. So their thoughts on taxation are likely to be heard throughout the Democratic Party, especially if it gains more leverage in D.C. in the coming years.
While the report makes several recommendations, including to boost funding at the Internal Revenue Service and to institute new “sin” taxes, its focus is largely on the corporate income tax—including the international tax system. The paper argues that the corporate tax is well-designed to tax windfall gains, including from companies in artificial intelligence, and can reduce inequality more efficiently than novel proposals such as wealth taxes. (Clausing expanded on this argument in a recent Financial Times piece.) If lawmakers follow its lead, expect to see many proposals in this area soon.
On international tax, the paper refers to a June report from Clausing published by the Hamilton Project. Here, Clausing calls for full U.S. implementation of Pillar Two—which would mean scuttling the side-by-side agreement which currently gives the U.S. an exemption—while also raising overall tax rates and making changes to other U.S. international tax provisions.
Under Clausing’s plan, the U.S. tax rate on the foreign profits of U.S. companies would be between 23% and 25% which is higher than the 15% minimum mandated by Pillar Two but still lower than the plan’s 27% rate for most domestic corporate income. In other words, while greatly increasing taxes on foreign income through higher rates and a broader base, it would still maintain a discount for foreign income—as does the current system. The report says this nod to territoriality is due to “competitiveness concerns,” as most other countries use a territorial system which exempts most or all of foreign income.
Of course, it will be at least two years before Democrats could control the White House along with Congress, and Republicans aren’t likely to agree to any plan that alters the system put in place by the Tax Cuts and Jobs Act and the One Big Beautiful Bill Act, as well as the hard-fought side-by-side exemption. But, the way things are looking, international tax will remain a live issue in Congress.
Noteworthy Items This Week
A liter of a drink containing 50 grams to less than 80 grams of sugar would be taxed at €0.26 ($0.29), rising to €0.32 for drinks containing 80 grams or more.
The tax would also apply to sugary concentrates used to prepare beverages, but not to alcoholic drinks, which generally are already subject to another excise tax.
Germany Proposes Tax on Sugary Drinks and Concentrates – Jan Stojaspal, Bloomberg Tax ($):
But that specification would exclude some companies from benefiting from the FDDEI deduction, by excluding significant parts of the kind of export income intended to be included in FDDEI, the National Association of Manufacturers said in a comment letter to the IRS released Tuesday.
The move would go beyond what the law requires to “impose an additional limitation that undermines the overarching purpose of the provision,” the NAM said..
Double Tax Fears In UN Talks Are Overblown, Economists Say – Natalie Olivo, Law360 Tax Authority ($):
All countries should "engage in good faith" at U.N. tax policy negotiations that are scheduled for Nov. 30 in Nairobi, Kenya, according to a statement from the Independent Commission for the Reform of International Capital Taxation. The group, which includes economists and former tax officials from around the world, contended that during past policy talks, there has been too much emphasis on the risk of double taxation.
"The issue is less double than zero taxation," the group said.
EU Countries Still Unconvinced by Proposed CFC Rules Changes – Elodie Lamer, Tax Notes ($):
The BEAT generally operates as a minimum tax that covers certain deductible, base-eroding payments large corporations make to foreign related parties. The U.S. Innovation and Global Competitiveness Act, introduced by Rep. Ron Estes of Kansas, would narrow when the BEAT applies to intercompany payments made overseas.
Estes said the bill keeps in place protections against profit shifting "while making sure U.S. job creators aren't hit with double taxation or penalized for routine business payments that don't erode our tax base."
In the case at issue, a dispute between Lithuanian tax authorities and plastic manufacturer Neo Group UAB, the court has been asked to clear up ambiguities surrounding the EU's Parent-Subsidiary Directive.
The PSD, adopted in 2011, exempts certain dividends and other profit distributions paid by subsidiaries to their parent companies from withholding taxes and eliminates the double taxation of such income at the parent-company level. The overall aim is to make it easier for companies to operate across EU borders.
Public Domain Superhero of the Week
Every week, a new character from the Golden Age of Comics, who’s fallen out of use.
This week’s entry: The American Crusader
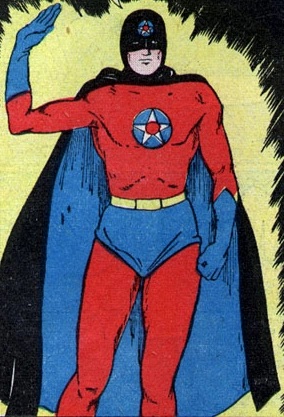
Debut Year: 1941
Debut Publication: Thrilling Comics #19
Origin Story: An lab accident involving an "atom smasher" turned this mild-mannered astronomy professor into a superhero, who uses a secret identity to fight criminals and Nazis during World War II.
Superpowers: Aside from flight, strength, and invulnerability, the accident gave the meek professor the confidence he needed to become a hero.
Eide Bailly's International Tax Team and our affiliates at HLB, The Global Advisory and Accounting Network, stand ready to assist with your worldwide tax needs.