Key Takeaways
- The OECD peer review process will determine how closely countries are following the 15% global minimum tax rules.
- The organization released guidance last week on some of the principles that will guide the “full legislative review."
- This could determine how various tax breaks are considered under the system, swinging tax revenue from one country to another.
- Canada revamps expensing rules to lure investment.
- Despite regulatory rollback, business organization seeks to invalidate transparency law.
Now that the Organization for Economic Cooperation and Development’s 15 percent global minimum tax is off and running—albeit, with some hiccups—what are the next steps?
One major phase on the horizon is the peer review, when participating countries will grade each other on how well they’re following the OECD rules. While this may seem like an afterthought, it could be one of the most important parts of the new system, when OECD officials and tax authorities will get into the nitty-gritty of how the minimum tax will work in practice. Billions of dollars in revenue could be on the line.
The OECD released some preliminary guidance on the peer review process on Friday, the “Terms of Reference and Assessment Methodology for the Full Legislative Review.” While this is far from a complete framework for a formal process that isn’t set to begin until next year, it sheds some light on how the officials hope to approach it.
One of the key tasks of the peer review will be judging countries’ qualified domestic minimum top-up-taxes. These are local taxes that countries have enacted on their own income, but based on the OECD’s Pillar Two methodology. They come first before any of the other Pillar Two taxes come into play. (And, despite the United States “side-by-side” exemption, they will still apply to U.S. companies.)
The rub is that every countries’ tax system is a little bit different, and each has its own litany of special tax breaks. During peer review, officials will determine whether a country’s QDMTT is following the guidelines closely enough, or if it has too many carveouts not compatible with the OECD’s own list of acceptable exemptions. If it’s the latter, the QDMTT will lose its “qualified” status and become just a DMTT, without the status as the first in the Pillar Two ordering rules. Other jurisdictions may be able to tax the covered income, and the country being examined will lose that revenue. And the purpose of whatever tax break they’ve tried to protect could be negated.
Indeed, one of the reasons the U.S. felt pressure to stay in the OECD system was to ensure they could participate in this crucial forum.
The OECD’s latest report doesn’t fully explain how it will judge individual countries’ tax systems, but it does outline some guiding principles.
In order to be a qualified domestic minimum tax, it must produce “functionally equivalent” outcomes as the Pillar Two rules—including that it be “structured so that it is in line with the architecture” of Pillar Two and it should not “systemically result” in tax revenue less than what the Pillar Two system would produce. Likewise, any variation from the system must either be expressly allowed in the guidance, or it should create different results.
This gives you an idea of the careful balancing act that countries will need to follow during peer review, as they reckon with the functioning of the Pillar Two system and the inherent nuances in the tax systems of sovereign nations.
Noteworthy Items This Week
The effort unveiled Tuesday by Prime Minister Mark Carney is aimed at strengthening Canada’s tax competitiveness and encouraging investment at a time when Canada is confronted with toughened trade environment and tariffs on exports to the U.S. The proposed change will improve productivity and strengthen the economy with what his government describes as one of the most-significant changes to Canada’s business tax system in half a century.
Corp. Transparency Law Unconstitutional, Justices Told – Kevin Pinner, Law360 Tax Authority ($):
A facial challenge to the CTA isn't mooted by the Department of the Treasury limiting its reach to foreign entities registered in the U.S., the NSBA said Wednesday in a reply supporting its petition to review the Eleventh Circuit's decision from December finding that the law is constitutional. Attacking a law's constitutionality shouldn't depend on whether the challenged provisions are currently enforced because "constitutional rights do not depend on — and cannot be mooted by — acts of executive grace," the group said.
Outermost Regions’ Pillar 2 Exemption Call Left Unanswered – Elodie Lamer, Tax Notes ($):
The outermost regions (French Guiana, Guadeloupe, Martinique, Mayotte, Réunion, and Saint-Martin; the Azores and Madeira; and the Canary Islands) are increasingly important as strategic outposts because of rising geopolitical tensions, but they continue to face socioeconomic challenges, a new dedicated strategy published by the commission September 10 says.
To account for their specific situation, article 349 of the Treaty on the Functioning of the European Union allows tailored application of EU law in those regions.
IRS Proposed Expense Rules Mute Tax Benefit in 2025 GOP Law – Lauren Vella, Bloomberg Tax ($):
Companies with an overall domestic loss, or ODL, are required by existing law to allocate it to their foreign-earned income. But, practitioners say, reallocating this loss to foreign income negates an expense allocation benefit in the 2025 tax law that would allow businesses to claim more credits for taxes they’ve paid abroad.
Treasury didn’t fully explain its rationale for not providing relief on the ODL issue, said Courtney Connell, a principal at EY and former chief tax counsel to the Senate Finance Committee. But it means that expenses that were “expressly diverted” from foreign income in the 2025 law could ultimately still reduce that income, she said..
Roughly $166 billion was paid in tariffs under the International Emergency Economic Powers Act, or IEEPA, which was overturned in February. Executives were initially reluctant to discuss their plans for pursuing refunds as they assessed criticism from the president and legal challenges from consumers seeking their share of the payouts.
They’ve been more forthcoming in recent months as the refunds started rolling in.
Public Domain Superhero of the Week
Every week, a new character from the Golden Age of Comics, who’s fallen out of use.
This week’s entry: Jaguar Man
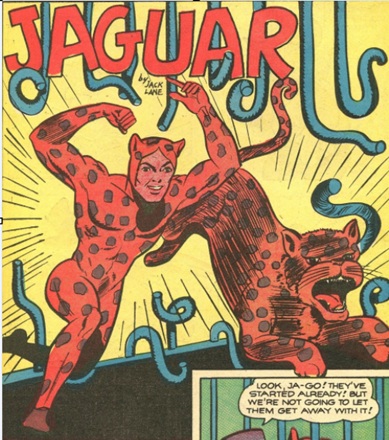
Debut Year: 1945
Debut Publication: All Great Comics #1
Origin Story: None known.
Superpowers: He can communicate with animals, and has panther-like strength and leaping abilities. Also has as a pet jaguar, Ja-Go.
Eide Bailly's International Tax Team and our affiliates at HLB, The Global Advisory and Accounting Network, stand ready to assist with your worldwide tax needs.