Key Takeaways
- With control of Congress, Democrats will look to legislation to showcase their agenda to voters.
- They’ll likely consider revenue options to offset those programs’ costs.
- International tax is one area where they could look for new revenue, but revenue estimates vary.
- Countries continue to implement Pillar Two minimum tax.
- U.N. tax committee hopes to change how tax disputes are resolved.
Democrats won a historic victory in the midterm elections earlier this month. Now comes the hard part.
While they will still not control all of government, Democrats are set to take majorities in both chambers of Congress in January with strong enough margins to control legislation. While anything they pass is likely to face a veto from President Trump, they can use bills as messaging to demonstrate their agenda to voters in the run-up to the 2028 presidential race. These proposals may not become law, and in a sense don’t matter—until they do.
In Washington, today’s theoretical proposal can often become tomorrow’s enacted law. Everyone will be paying close attention to the specific proposals the party chooses.
With affordability still the buzzword following the midterm campaigns, Democrats will likely focus on measures to address voters’ pocketbooks, including increasing healthcare coverage, food stamp benefits, and other social programs. They’ll also face tricky questions about whether to include proposals to raise tax revenue, and which proposals to consider.
It’s easy to build campaign rhetoric around slogans like “Tax the Rich” and “Make Billionaires Pay Their Fair Share.” But enacting these ideas into legislation will be much more complex and fraught, with problems of constitutionality, administrability and fairness.
This is where international tax comes in. Plugging alleged loopholes in the current tax code that allow global tax shifting and offshoring is something most Democrats could agree on, in principle. But the devil, as always, is in the details, starting with the revenue estimates for how much a change in the international tax rules would bring in.
This isn’t like 2017, when there was $2.6 trillion in accumulated offshore earnings for the U.S. to capture to offset tax cuts elsewhere. Experts have strong disagreements about how much global profit-shifting still occurs, as well as how much represents erosion of the U.S. tax base. There are also a lot of questions about the amount of revenue proposals to change international tax rules, such as the tax on Net CFC Tested Income (NCTI), would bring in.
In 2023, the Joint Committee on Taxation estimated that enacting Pillar Two, the Organization for Economic Cooperation and Development’s 15% global minimum tax, would bring in $65.5 billion over 10 years, compared to a scenario where the U.S. doesn’t implement Pillar Two but the rest of the world does. That information is well out of date by now, especially since Congress changed the international tax rules in the 2025 One Big Beautiful Bill Act, and the U.S. entered an agreement with the OECD to exempt U.S. companies from much of Pillar Two. But it provides a sense of the scale of revenue—which is a significant amount of revenue, but small in comparison with Democrats’ ambitious plans.
The picture has changed since then, and will certainly change more between now and whenever these proposals might have a chance at becoming law. In the meantime, countries will continue to carry out the Pillar Two plans, collecting new taxes from multinational companies and leaving less for the U.S. to get later.
That makes for complicated policymaking, and even more complex politics.
Noteworthy Items This Week
The Australian Treasury started a public consultation November 11 on draft legislation that would partially implement the pillar 2 side-by-side package issued January 5 by the OECD inclusive framework on base erosion and profit shifting.
The bill proposes amending the Taxation (Multinational—Global and Domestic Minimum Tax) Rules 2024, Australia’s pillar 2 regulations, to introduce the elective side-by-side safe harbor. Under the measure, large multinational enterprise groups are shielded from the global anti-base-erosion rules if they are headquartered in jurisdictions that enforce a qualified side-by-side regime.
UN Tax Talks to Look at Limiting Existing Dispute-Tool Access – James Munson, Bloomberg Tax ($):
The UN intergovernmental negotiating committee’s secretariat released two draft agreements late Monday that include a proposal to discuss a new article on restricting dispute resolution methods. The drafts were released ahead of the committee’s next major meeting, Nov. 30 to Dec. 10 in Nairobi, Kenya.
Many delegations have said they oppose the use of third-party arbitrators to resolve disputes, a method found in many bilateral investment deals but less prevalent in tax treaties. Developing countries have criticized arbitration’s cost as well as perceived power asymmetries and limits on sovereignty, while business groups have supported arbitration tribunals as providing a consistent application of the rule of law.
U.S. Is Pushing for More Proxy-Based Pillar 2 Safe Harbors – Stephanie Soong, Tax Notes ($):
The introduction of safe harbors has helped simplify the global minimum tax rules and reduce taxpayer compliance burdens, but they could be more powerful when they’re combined with proxies, Treasury Deputy International Tax Counsel Isaac Wood said November 12. He spoke at a tax conference in Washington organized by the International Bar Association.
Seeking the Center in International Tax Policy – Mindy Herzfeld, Tax Notes ($):
It’s too easy to say that a government split between large Democratic majorities in Congress and a lame-duck Republican president will mean little progress on international tax policy — hardly the top priority on anyone’s agenda. But the reality is that there are many areas in which ongoing developments in international tax — both multilateral and domestic — can’t simply be put on hold for two years. Moreover, the ambitious social welfare agenda of many new members will require an equally ambitious revenue-raising program. U.S. multinational taxpayers used to familiar congressional ears will now be meeting some Democratic lawmakers with a populist bent who may be intent on using corporate tax payments (or the lack thereof) as a tool for advancing a progressive agenda.
The Inclusive Framework on Oct. 30 released a statement of outcomes regarding their latest plenary meeting that includes a section on member countries’ “dialogue on the tax challenges arising from the digitalization of the economy.” It’s clear that this dialogue has only just begun.
Public Domain Superhero of the Week
Every week, a new character from the Golden Age of Comics, who’s fallen out of use.
This week’s entry: Ace of the Newsreels
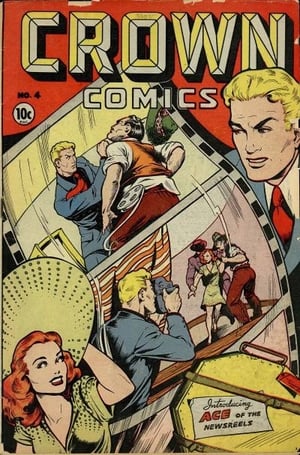
Debut Year:1945
Debut Publication: Crown Comics #4
Origin Story: A photographer and journalist, he fights crime while also reporting the news with his sidekick, Jessica.
Superpowers: No superpowers or even costume, but his fists and camera are more than enough.
Eide Bailly's International Tax Team and our affiliates at HLB, The Global Advisory and Accounting Network, stand ready to assist with your worldwide tax needs.