Key Takeaways
- The Senate passed a bipartisan tax administrative bill, making several changes to the IRS and the tax code.
- The bill includes changes to make the taxpayer experience smoother and to bolster the rights of taxpayers in disputes.
- It also includes changes to the IRS Appeals Office, to make it more independent.
- Lawmakers seek to protect deduction for top salaries on public sports teams.
- Democrats claim Treasury is twisting law on scholarship credits.
In this partisan age, it’s hard to believe that any major bill could be passed in Congress with near-unanimous support.
It’s looking like that could happen, however, with legislation advancing in both chambers to improve the taxpayer experience at the Internal Revenue Service, and make other administrative changes to the tax code. The Senate recently passed, in a unanimous voice vote, legislation with more than 60 tax administrative provisions. The House has been advancing many of the same, or similar, items in individual bills.
None of these proposals, individually, would be considered huge accomplishments. But together, they amount to a major piece of legislation, with effects that will likely be felt by millions of Americans.
Though, whether lawmakers can get it across the finish line during a packed lame duck session is still an open question.
The package includes measures to improve IRS services by making its callback system more responsive, creating a dashboard of wait times, and improving online accounts so that taxpayers can have a better sense of the status of their returns and refunds. It also would require the IRS to upload information on printed returns through a barcode, to reduce the agency’s persistent backlog of physical tax filings.
The Senate bill also includes measures meant to smooth out potential tax controversies, before they make it to court. This includes authorization for the IRS Independent Office of Appeals to hire its own counsel, rather than relying on the IRS Chief Counsel, and to directly hire staff outside of the IRS. This would bolster the office’s independence and, according to supporters of the legislation, make it more likely to resolve disputes before they head to court.
“The TAS Act would build on IRS Appeals’s existing statutory framework with a set of targeted reforms to further separate IRS Appeals from the agency’s enforcement functions and ensure that taxpayers have a meaningful opportunity to resolve disputes administratively before resorting to litigation,” wrote Jonathan W. Burks, senior vice president of policy for the U.S. Chamber of Commerce, in a recent open letter to the Senate.
(Some interesting IRS history: What is now the U.S. Tax Court grew out of the first IRS appeals board. The current Office of Appeals began as the IRS Special Advisory Committee in 1927.)
There isn’t a direct House version of the Senate’s Appeals changes yet. But both the House and Senate packages include provisions to bolster the Taxpayer Advocate Service and some functions of the U.S. Tax Court, as well as some provisions to improve oversight of IRS adjustments when they are first proposed.
One thing the Senate bill does not include is an increase in IRS funding. While it does free up some funds for certain functions, overall it would cost $49 million over the next 10 years–barely a dent in the federal budget. While lawmakers can come together to support these changes, the IRS budget remains a contentious, partisan issue.
Recent Tax Pieces:
Bipartisan Bill Would Address Tax Parity for Public Sports Teams – Cady Stanton, Tax Notes ($):
The three publicly held sports teams in the United States and the members of Congress who represent them have raised concerns that the limitation could put those teams at an economic and competitive disadvantage when it goes into effect.
“For publicly traded professional sports organizations like the Atlanta Braves, this means players and other on-field personnel will be swept into a tax rule designed around executive compensation,” Sen. Katie Britt, R-Ala., who cosponsored the bill with Warnock, said in a statement. “Our bipartisan bill makes a targeted correction by excluding athletic personnel from that additional five-employee category while leaving the existing executive-compensation rules in place.”
Democrats Slam Scholarship Rule as Costly to Public Schools – Chris Cioffi, Bloomberg Tax ($):
The divisive policy gives donors a tax break for donating to scholarship-granting organizations that provide financial assistance for low- to middle-income students.
“This throws doubt upon Treasury’s interpretation of many provisions of the code, creates a great deal of uncertainty in the administration of our tax laws, and could balloon the deficit,” the lawmakers said.
Restyling Crypto Tax and Market Structure Bills – Lee A. Sheppard, Tax Notes ($):
“The bill kills the argument that tokens newly minted by a validator are self-created property. Although the bill leaves open the timing of inclusion for newly minted tokens, it clearly treats newly minted tokens as income, to be taxed at ordinary rates,” said Jason Schwartz of CahillNXT.
The Ins and Outs of OZ: Information Reporting and Decertification – Marie Sapirie, Tax Notes ($):
The proposed rules offer key clarifications for QOFs and attempt to balance interests and policy considerations while mostly adhering to the statutory language. Although the rules were anticipated by the OBBBA, there will likely still be a period of education and implementation ahead for QOFs.
Opinion: Kelly’s AI Tax Bill Struggles to Link Tech With Economic Harms – Andrew Leahy, Bloomberg Tax:
When there’s a direct connection between a levy and the economic harm it’s targeting, not much analytical or rhetorical work is necessary to explain the policy logic. A tax on every gallon of potable water a factory uses in production to offset the costs of that water consumption is straightforward and intuitive.
By contrast, a tax based on how many times that factory opens its front door in a day, justified to offset the cost of water use, demands much more explanation. At that point, the critical question isn’t just how much is being taxed, but what opening the door has to do with water consumption.
Public Domain Supervillain of the Week
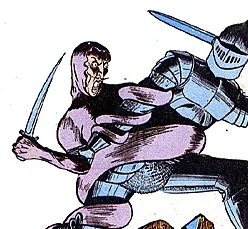
Every week, a new villain from the Golden Age of comics, who's fallen out of favor.This week's entry: Rubberman.
Debut Year: 1943
Debut Publication: Air Fighters #6
Arch-nemesis: Iron Ace (see October 2025 post)
Origin Story: He ran a rubber factory in Nazi Germany, before his plant was bombed, turning him into literal rubber.
Abilities: He has the properties of rubber, including to stretch, bounce, and deflect bullets. (A bit like DC Comics' Plastic Man, who debuted two years earlier.)