Key Takeaways
- Congressional committee OKs bipartisan crypto tax bill.
- Film tax credit picks up steam.
- Tax gap disappears from data.
- Taxpayer data at risk, IRS watchdog says.
- National Cheeseburger Day.
In Congress
House Panel Moves Crypto Tax Measure With Bipartisan Support - Chris Cioffi, Bloomberg Tax ($):
Horsford praised the bill, saying it represents progress on many issues but isn’t the final word on crypto and taxation.
“The package establishes rules in several areas, while leaving other questions for further consideration,” Horsford said during the markup Wednesday. “Today’s vote does not end that work.”
Film Credit Caucus Gets Positive Early Buzz - Jared Serre, Tax Notes ($):
Friedman, a former film producer elected to Congress in 2024 to represent the Los Angeles-area city of Burbank, joined with five other lawmakers to form the initial caucus. The bipartisan effort is focused on strengthening and expanding film production across the country, according to a release.
Is There Any Hope for the ACA Premium Tax Credits? - Kelsey Brooks, Tax Notes ($):
The healthcare tax credits were established in the American Rescue Plan Act of 2021 and extended through December 31, 2025, by the Inflation Reduction Act. Democratic efforts to extend the premium enhanced tax credits into 2026 led in part to a 43-day federal government shutdown that ended November 12, 2025, with the passage of an appropriations bill that didn’t include a provision for the ACA subsidies.
ESOPs
The legislation is expected to provide long-awaited legal clarity for ESOP transactions — reducing costly litigation, drawing insurers back into the market, and potentially unleashing a wave of new ESOPs that advocates say has been suppressed for decades by regulatory uncertainty.
“What Congress is doing is looking at the state of class action litigation and saying we need to do something with the adequate consideration standard, because it’s become a disincentive for folks to create ESOPs,” said Andrew Salek-Raham, a principal at Groom Law Group.
At the IRS
Billions in Taxes Go Unpaid. Under Trump, the I.R.S. Won’t Say How Much. - Andrew Duehren, The New York Times ($):
Beyond illustrating the extent and sources of tax noncompliance, the tax gap has also been a figure often cited to argue for giving more resources to the I.R.S. In 2021, Charles P. Rettig, Mr. Trump’s first-term pick to lead the I.R.S., speculated that the tax gap could be as much as $1 trillion a year, a figure much larger than the I.R.S. estimate at the time, as he called for a bigger budget for the agency.
IRS tax debt agreements have plummeted: 'I've never seen a number that low,' taxpayer advocate says - Greg Iacurci, CNBC:
The IRS accepted about 5,500 “offers in compromise” during the 2025 fiscal year — a 57% decline from 2023, when the agency accepted about 12,700 offers, according to agency data.
The IRS offer in compromise program allows taxpayers to settle their tax debts for less than the full amount owed. On IRS.gov, the agency describes it as a “legitimate” option for those who can’t pay their debt or who would suffer financial hardship doing so.
Watchdog: IRS Risks Taxpayer Data Without Cybersecurity Changes - Erin Slowey, Bloomberg Tax ($):
The Treasury Inspector General for Tax Administration found in a report that the IRS’s cybersecurity program wasn’t effective because some of its functions weren’t at advanced levels.
The report said 86% of the sampled information systems had critical vulnerabilities not remediated within 30 days, as required.
TIGTA is required as part of the Federal Information Security Modernization Act of 2014 to conduct an annual review of the IRS’s security programs.
Conservation Easement Lawyers Find Hope Beyond Court Losses - David Schultz, Bloomberg Tax ($):
The IRS argues that taxpayers should only look at sales of comparable properties when valuing their land, not at what the land could be used for if its economic value were maximized, Bradford said. But there hasn’t yet been an opinion fully endorsing the IRS’s viewpoint from the Eleventh Circuit, which is hearing a large number of these cases because many conservation easements are located in the deep South, she said.
“While the opinions have largely affirmed the Tax Court, they haven’t actually said anything that’s in an overarching way bad for taxpayers,” she said.
Trade
Axle of Dearborn and the Death of De Minimis - Nana Ama Sarfo, Tax Notes ($):
For the U.S. Court of International Trade, the answer is yes.
In August the U.S. Court of International Trade addressed this question in Axle of Dearborn Inc. v. Department of Commerce, slip op. 26-94 (Ct. Int’l Trade Aug. 13, 2026), in which a three-judge panel held that President Trump’s IEEPA authority allows his administration to suspend duty-free treatment for low-value imports.
Opportunity Knocks
Opportunity Zone Investors Eager for More Guidance Ahead of 2027- Erin Schilling and Shannon Najmabadi, Bloomberg Tax ($):
For the U.S. Court of International Trade, the answer is yes.
In August the U.S. Court of International Trade addressed this question in Axle of Dearborn Inc. v. Department of Commerce, slip op. 26-94 (Ct. Int’l Trade Aug. 13, 2026), in which a three-judge panel held that President Trump’s IEEPA authority allows his administration to suspend duty-free treatment for low-value imports.
Blogs & Bits
Three Facts Straightening Out the Debate Over Bonus Depreciation, The Tax Foundation blog. "Expensing for capital investment is not a special tax break."
IRS Extends Drought Tax Relief for Farmers and Ranchers, Kelly Phillips Erb, Taxgirl. "This past year has been very dry in many parts of the U.S., which has been particularly devastating for farmers and ranchers. As a result, the IRS has announced additional tax relief for those who were forced to sell or exchange livestock because of drought conditions."
New Census Data Show Importance of Refundable Tax Credits and Need for Improvements, Joe Hughes, Institute on Taxation and Economic Policy. "The new Census data show the enormous impact that refundable tax credits have on poverty – particularly child poverty."
What Day Is It?
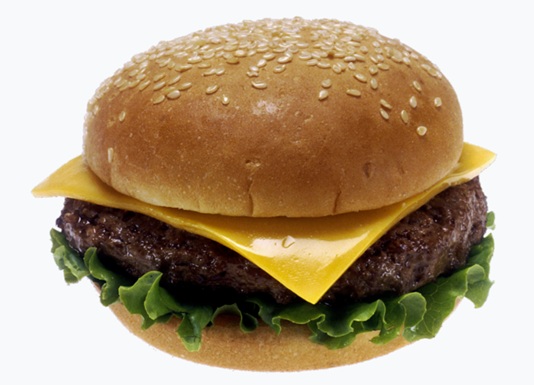
It's National Cheeseburger Day! Not too late for an outdoor cookout to celebrate a great American meal.